Thesis
Residential, C&I and utility: three solar markets that don't look alike
In Mexico, the word «solar» names three different businesses: a home rooftop, the industrial plant that generates for itself, and the park that sells to the grid. The customer, the permit, the risk and who finances it all change.
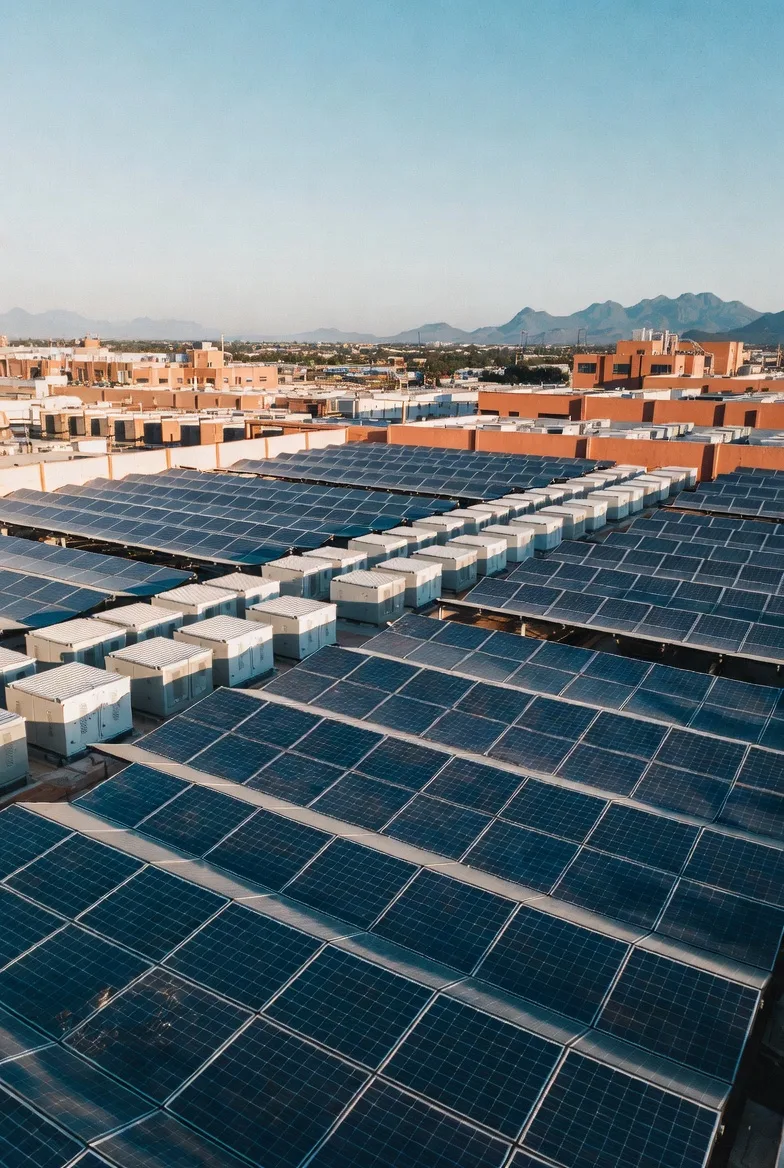
On-site generation, self-supply and storage for industrial plants in the Bajío.
Let's discuss your projectBajío Ventures · March 2026
When someone in Mexico says “investing in solar”, they may mean three things that share a technology and little else: a home rooftop, the industrial plant that generates for itself, and the park that sells power to the grid. The modules are the same; the customer, the tariff they compete against, the permit, the risk and who puts up the money are entirely different. Mixing them up is the fastest way to misjudge an opportunity.
The picture at the end of 2024
Mexico closed 2024 with 12,589 MW of solar, according to Asolmex: 8,167 MW utility-scale and 4,422 MW of distributed photovoltaic generation (plants under 0.5 MW, the threshold in force until 2025). But the two blocks moved in opposite directions: utility-scale added 523 MW in 2024, its lowest figure in seven years (its peak was 1,768 MW in 2019), while distributed generation added 1,086 MW, a record.
Within distributed generation, two markets coexist:
| System size | Contracts | Capacity | Reading |
|---|---|---|---|
| 0–10 kW | 466,203 (90%) | 1,997 MW (45%) | Residential and small business |
| 250–500 kW | — | 899 MW (20%) | C&I: warehouses, plants, shopping centers |
| Total distributed generation | 518,019 | 4,448 MW | All technologies; 99.4% solar |
Source: CRE distributed generation report at year-end 2024, via pv magazine. Intermediate size bands make up the total.
Nine out of ten contracts are household rooftops, yet a fifth of the capacity sits in the 250–500 kW band alone. In other words: residential wins on count; C&I wins on megawatts per project.
Three markets, side by side
| Residential | C&I | Utility | |
|---|---|---|---|
| Typical size | 3–10 kW | 100 kW – 20 MW | 20 MW – hundreds of MW |
| Where it sits | Home rooftop | Roof, parking lot or land next to the load | Dedicated land, connected to transmission |
| What it competes against | Residential tariff (1 to 1F, or DAC) | Industrial tariff (GDMTO, GDMTH) with demand charges | Wholesale price or an offtake contract |
| Regime (2025 LSE) | Distributed generation, no permit | < 0.7 MW no permit; 0.7–20 MW self-supply permit | CNE permit, aligned with binding planning |
| Who buys the power | The household itself | The plant itself (or a self-supply group) | CFE, suppliers or large users |
| Main risk | Tariff subsidy | Customer credit and its permanence at the site | Permit, interconnection and price |
| Who finances | The household, on credit or cash | The company, a lessor or a developer under contract | Project equity and long-term debt |
Residential: the subsidy decides
A residential system competes against the household’s tariff, and in Mexico that tariff is subsidized for the vast majority. A low-consumption home on tariff 1 pays so little per kilowatt-hour that a rooftop takes too long to pay back. The case changes completely when average consumption exceeds the threshold —250 kWh a month on tariff 1— and the household falls into DAC, the unsubsidized high-consumption residential tariff: there, the savings are immediate.
That is why residential solar spreads by word of mouth and by climate: it concentrates in the hot, middle-to-upper-income cities of the north and west. It is a volume, retail, installer-driven market; for an institutional investor, the interest lies in financing it as a portfolio, not project by project.
C&I: the market that changed in 2025
A commercial and industrial system competes against an unsubsidized, time-of-use tariff with capacity and distribution charges. Its economics depend not only on the kilowatt-hours it saves but on how much and at what time the plant consumes: a facility that runs during the day uses almost all of its generation; one whose demand peaks in the evening needs storage to cut its capacity bill.
The Electricity Sector Law of March 2025 widened this market in two steps:
- Up to 0.7 MW (previously 0.5 MW), a plant is treated as distributed generation and needs no permit.
- From 0.7 to 20 MW, there is a specific interconnected self-supply permit, whose application format the CNE published in August 2025. The self-supply rules published on 12 December 2025 also allow self-supply groups —several users sharing infrastructure— and the sale of surplus power, exclusively to CFE, at 0.9 times the lower of the last auction’s cost and the local marginal price.
C&I is the segment where generation is built next to the load, without waiting for the grid to arrive. Its risk is not the technology: it is the customer. A 15-year contract is worth what the company’s credit and its commitment to stay at that site are worth.
Utility: the market waiting on planning
Utility-scale solar sells power to the grid, so it competes against the wholesale price and depends on three things it does not control: the permit, the interconnection and a buyer. Since long-term auctions were cancelled, the natural buyer has become scarce; under the 2025 law, growth runs through SENER’s binding planning and schemes with CFE participation. Hence the drop to 523 MW in 2024.
It is the segment with the largest scale and lowest cost per megawatt, but also the longest timelines and the most concentrated regulatory risk. Where the grid is saturated, a park can be ready to build and have nowhere to connect.
What it means for the Bajío
Guanajuato closed 2024 as the fourth-largest state in distributed generation, with 290 MW across 27,434 contracts. Its average system is around 10.6 kW, against about 7.2 kW in Jalisco, the leader (658 MW across 90,876 contracts): a sign that industrial rooftops weigh more than household ones in Guanajuato. Aguascalientes, by contrast, is one of the country’s utility-scale hubs.
For a region whose demand is driven by industrial parks, the conclusion is direct: the segment with the best balance of risk, timeline and size is C&I, especially in the new 0.7–20 MW band, paired with storage wherever the tariff rewards shaving peak demand. Residential will keep growing on its own; utility-scale will return when the grid and planning allow it. C&I can be built today.
Sources: pv magazine, distributed generation in Mexico reaches 4,447.92 MW in 2024, Feb 2025 · El CEO / Asolmex, four states hold 60% of utility-scale solar, May 2025 · Expansión, solar energy in Mexico lives two realities, Sep 2025 · Greenberg Traurig, CNE agreement on 0.7–20 MW self-supply permits, Aug 2025 · Pérez-Llorca, self-supply DACGs published, Dec 2025
Bajío Ventures — a Mexican energy-infrastructure investment group based in Guanajuato: capital, a data platform on the region’s industrial base, and a German industrial channel, with its own advisory presence in Berlin.
On-site generation, self-supply and storage for industrial plants in the Bajío.
Let's discuss your projectThis article is also available in Spanish. Read in Spanish